Reverse Mortgage Readiness Assessment
Could your home help you pay the bills?
You worked hard for this home. Now the bills may take more of your check. See if a reverse mortgage is worth a look.
It is a loan. You still pay home tax, keep insurance, and care for the home. The loan can grow over time.
What you can find out
Start with your home and your bills.
If your check stays the same and your bills go up, it helps to know your choices.
See what may help
Think about the bills you want help with each month.
See what it may cost
Learn what you still pay and why the loan can grow.
Pick a next step
Read more, look at the math, or talk with Jim.
How the check works
Tell us a bit
Start with a few facts about your home and what you need.
Get a next step
Your answers help you see what is worth a closer look.
Take your time
You can read more or ask Jim to talk it through with you.
What stays the same?
- Stay in your home as long as you meet the loan rules.
- Keep paying home tax and insurance. Keep up with repairs.
- An FHA-insured reverse loan has no set monthly loan payment.
- Interest and fees can grow the loan. Your family may get less from the home later.
Make time for the talks that matter.
Talk it through with your spouse or someone you trust. Here are a few things you can ask Jim.
- Can both of us stay in the home?
- What will we still pay each month?
- What could be left for the kids?
One person to help you compare lenders.
Jim can look at more than one reverse mortgage lender. Ask him to put the costs, loan terms, and cash you may get side by side.

Lender and loan options depend on your home and where you live.
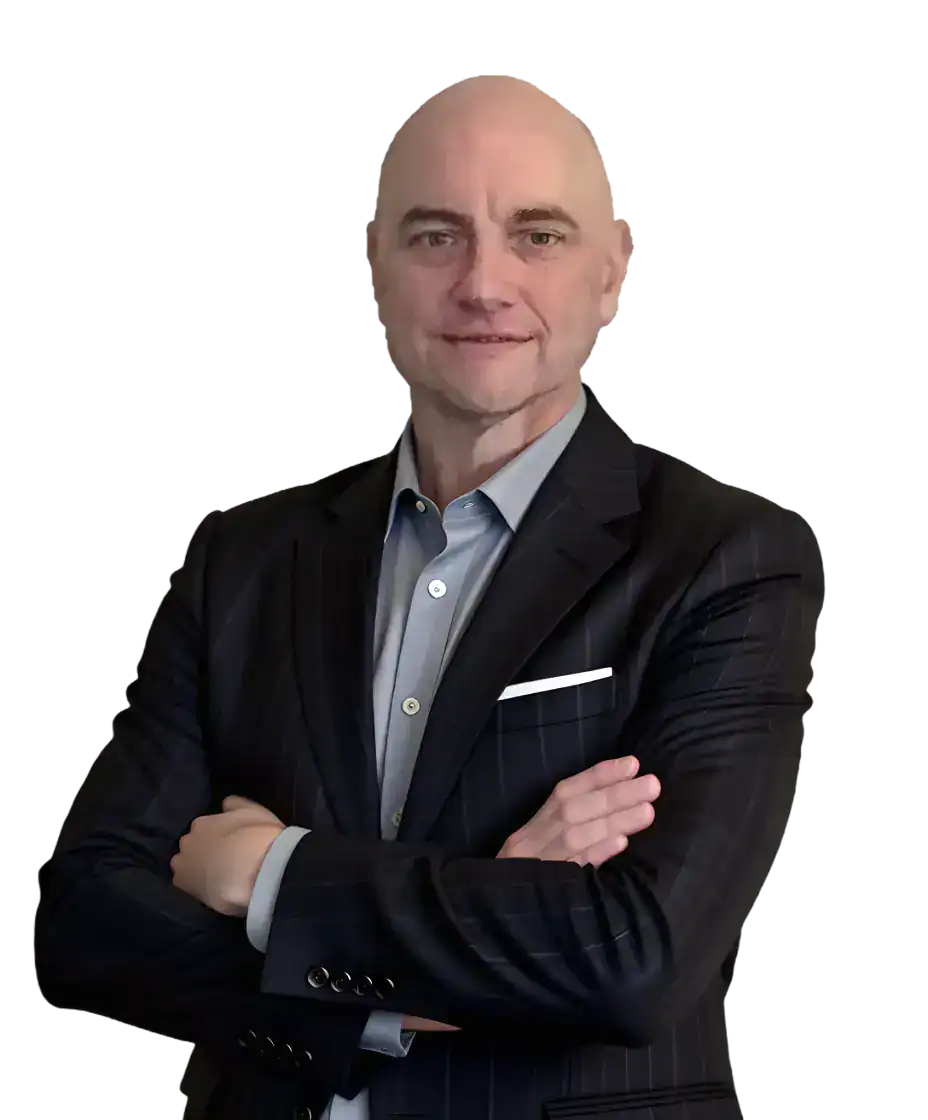
Meet Jim Mucci
Get clear answers from Jim.
I help people in Michigan make sense of home loans. Bring your questions. You can ask a friend or someone in your family to join us.
“He takes the time to listen and thoroughly explain various options that are in my best interest.”
TaJuana Jeter, Treeside Financial home loan client
James “Jim” Mucci · Mortgage Loan Originator · NMLS #138693
Client reviews
What clients say about Jim
These reviews are from people who worked with Jim on home loans.

Everything went smoothly and I was very pleased
I finished my loan process with James last month. Everything went smoothly and I was very pleased with the end results. James has attention to detail and puts his clients first. He takes the time to research and resolve anything that comes up. He’s also excellent at guiding clients through the process. I’ve recommended him to friends as I trust him.

Easy, Informed, and Always Reliable!
James was easy to work with on our mortgage refinance. He has done a good job keeping us up to date on other offerings, and we do plan to use his services, again.

Knows the business and easy to work with!
James was my mortgage broker for my 2009 refinance. He was very easy to work with and truly knows the business. I hope to work with him again in the future!

Expert at explaining the all the options
Jim has done a great job working through mortgage finance options with me. I was nervous about an online mortgage, but Jim’s deep knowledge and expertise eased my fears.

Great Rates, Great Service—Twice!
I have refinanced with Jim (Treeside Financial) twice. He has great rates and does a good job.

Amazing job navigating the process
I worked with James as my mortgage broker in the process of buying my home back in November of 2008 right after the housing market imploded. James did an amazing job helping my wife and I navigate the challenging process of not only finding a good lender at that time, but also guiding us through the tumultuous closing process. I would recommend James strongly to anyone.

Listen, Explain, and Puts My Best Interest First!
I was referred to Jim (at Treeside) by a good friend and colleague. I found him to be very easy to work with. He takes the time to listen and thoroughly explain various options that are in my best interest. James is someone that I call upon for all of my mortgage needs and I highly recommend him.

Made My Refinace Easy!
Jim, from Treeside Financial, answered my questions very quickly and accurately and was very easy to work with. He made the mortgage refinance process (more complicated with paperwork these days) as easy as possible.
Take it one step at a time.
You can do the check first and ask for help when you want it.
Start my assessmentYou choose what comes next.
Your home and your family
Questions people ask first
Do I still own my home?
Yes. You stay on the title. The loan uses your home as security. You must live there as your main home, pay the tax and insurance, and keep it in good shape. If you do not keep up, you could lose the home.
Can my spouse stay?
A spouse who is on the loan can usually stay if they meet the rules. A spouse who is off the loan may be able to stay under some rules. Ask before you sign.
What will my kids get?
The loan has to be paid back when it comes due. Your family may sell the home or find a way to pay the loan to keep it. What is left after the sale costs and loan goes to your estate.
What will the loan cost?
There are fees. The loan also adds interest over time. That can leave you with less of the home’s value later. Ask to see the costs and what you might owe in a few years.
What if I still owe on my home?
You may still be able to get the loan. Your old home loan must be paid off when the new loan starts. That can leave you with less cash to use.
At your pace
Ready to look at your choices?
Start with the check. Then take the next step that makes sense to you.
Start my assessmentThis check helps you learn about your options. It does not apply for a loan, approve a loan, or tell you how much you can borrow.